Paying rent on time doesn't have to disappear the moment you hand over your payment. Rent reporting services can add that payment history to your credit file, and new federal mortgage rules are starting to give it real weight for the first time. Here's what changed in 2025, why it matters if you're working toward homeownership, and how a tool like Ava's Rent & Utility Reporting fits in.
What's in This Article?
1. Why Is Homeownership So Hard for Young Adults Today?
2. Why Don't Rent Payments Count Toward Credit History?
3. Is Rent Reporting Finally Becoming a Real Credit-Building Tool?
4. How Does Ava's Rent & Utility Reporting Actually Work?
5. What's the Difference Between Rent Reporting and a Credit Builder Loan?
6. Redefining What It Means to Build Credit
7. Frequently Asked Questions
TL;DR
● Roughly 1 in 8 U.S. adults still have limited or no credit history, and many are renters whose on-time payments never reach a credit bureau.
● Rent reporting is growing. TransUnion found that 13% of consumers had rent payments reported to the credit bureaus in 2025, up from 11% in 2024.
● A July 2025 FHFA policy now lets Fannie Mae and Freddie Mac lenders use VantageScore 4.0, a scoring model that factors in rent payment history, when underwriting a mortgage.
● Tools like Ava's Rent & Utility Reporting let you report the rent you already pay to TransUnion, without taking on new debt.
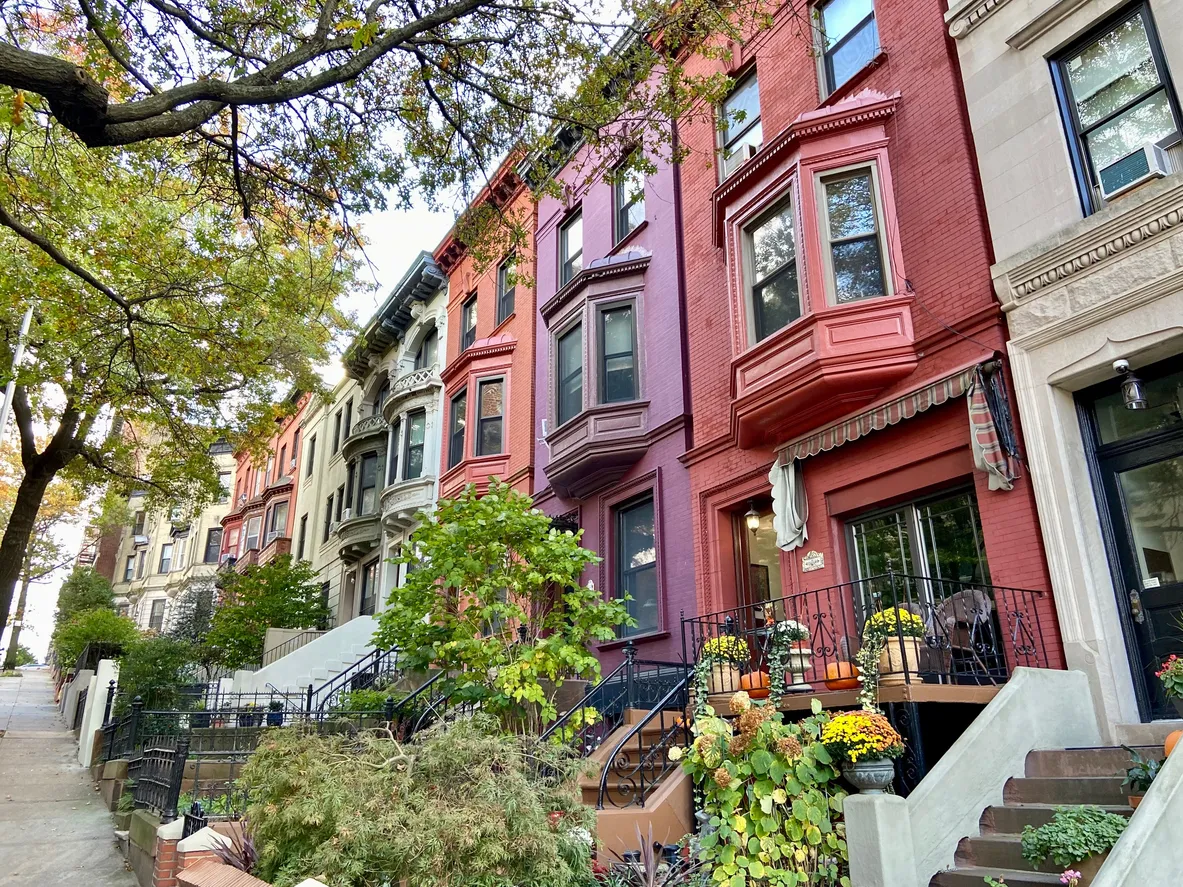
As a kid, I walked past a purple house with turquoise trim on my way to school. The door was a forest green that didn't quite match the rest of the house, but somehow it worked. The steps were burgundy, half-hidden under potted plants and soil the wind had scattered. Every other house on the block looked the same: beige, tidy, unremarkable. I used to wonder why only one homeowner chose color.
I made a promise to myself then. When I grew up, my home would be colorful too.
Two decades later, that promise still stands. The path to owning a home, though, feels further away than it used to.
Why Is Homeownership So Hard for Young Adults Today?
Homeownership has gotten harder for younger generations because home prices have outpaced income growth, while the traditional credit-building path largely left renters out.
Thirty years ago, young adults followed a fairly predictable script: college, a full-time job, marriage, a house, often all before turning thirty. A white picket fence wasn't just a metaphor. It was close to the standard.
That script looks different now. According to the National Association of Realtors' 2025 Home Buyers and Sellers Generational Trends Report, published in November 2025, first-time buyers made up just 21% of the market for the year ending mid-2025, the lowest share since NAR began tracking the data in 1981. The median age of a first-time homebuyer has climbed to 40.
Home prices, meanwhile, have surged well past income growth. Many Gen Z and younger millennial renters are watching housing costs rise faster than their paychecks. The old formula, save 20%, buy a starter home, build equity, doesn't work the way it used to for most people under 35.
Key Takeaway: The traditional path to homeownership has narrowed for younger buyers, which is part of why alternative ways to build a credit profile, like rent reporting, matter more than they used to.
Why Don't Rent Payments Count Toward Credit History?
Traditional credit scoring models were built around debt products: credit cards, auto loans, mortgages. Rent, despite being most renters' largest monthly expense, was never automatically part of that picture.
According to a June 2025 technical correction from the Consumer Financial Protection Bureau, about 2.7% of U.S. consumers have no credit file at all, and another 9.8% have a file too thin to produce a score. Combined, that's roughly 1 in 8 adults with limited or no credit history. That's a meaningful downward revision: the CFPB's earlier, widely cited estimate, often rounded to 45 million Americans, was based on 2010 data that the bureau has since said should be "roughly cut in half" after a methodology update.
Many of the people in that group are renters who have never missed a payment on their biggest monthly bill, but those payments simply don't show up on a credit report.
The irony is hard to miss. Renters demonstrate financial reliability every month. Traditional credit systems weren't built to see it.
That's starting to change.
Is Rent Reporting Finally Becoming a Real Credit-Building Tool?
Yes. Rent reporting is becoming a legitimate, growing credit-building strategy, and it's picking up policy support at the federal level.
According to TransUnion's September 2025 rent-reporting analysis, 13% of consumers had rent payments reported to the credit bureaus in 2025, up from 11% in 2024. That share has been climbing as more property managers and reporting tools get involved.
Here's the bigger shift. In July 2025, the Federal Housing Finance Agency announced that lenders selling loans to Fannie Mae and Freddie Mac may now use VantageScore 4.0, a scoring model that factors in rent, utility, and other alternative payment data that the older FICO model doesn't consider, when underwriting a mortgage. It isn't a mandate. Lenders can still choose the traditional model. But it's the first time on-time rent payments have had a direct route into a federally backed mortgage decision.
Separate research backs up the shift. A randomized study published by the Urban Institute in June 2025 followed 269 renters and found that positive-only rent reporting cut the share of participants with no credit score in half, from 16% to 8%, and meaningfully increased their odds of reaching a near-prime score. For people who are credit invisible, establishing a score at all is often the first real step toward accessing credit products.
Paying rent on time has always been a sign of financial responsibility. The system is finally starting to catch up.
How Does Ava's Rent & Utility Reporting Actually Work?
Ava's Rent & Utility Reporting works by securely linking your existing rent and utility payment accounts and reporting your on-time payment history to TransUnion.8
Here's what makes it different from most credit-building tools:
● No new debt required. You're not taking out a loan or opening a credit card. You're getting credit for bills you're already paying.
● No hard credit check to apply. Ava's Rent & Utility Reporting is not a lending product, so signing up does not involve a hard inquiry, the kind of credit check that can temporarily affect your score, the way applying for a loan or credit card typically would.
● No interest charges. This is a reporting tool, not a lending product. A membership fee applies for access to Ava's products.10
● Reports to TransUnion. Your rent and utility payment history is reported to one of the three major credit bureaus.8
It's not a shortcut, and results vary. But it's a way to make the financial consistency you're already showing, paying rent, keeping the lights on, managing bills month after month, visible to lenders.
Key Takeaway: For renters who've felt shut out of traditional credit-building tools, having that history reported at all can matter. Adding a new account and a longer payment history can factor into a stronger credit profile over time, though outcomes depend on your full credit file and are never guaranteed.
Redefining What It Means to Build Credit
A credit history is one of the more overlooked gateways to opportunity, and not just for homeownership. It can factor into loan approvals, car insurance rates, apartment applications, and in some cases, job offers.
Where previous generations measured adulthood in mortgages and milestones, a lot of people now measure it in financial stability, autonomy, and options. The next version of the American Dream might not start with a deed. It might start with something smaller: building a credit history.
A system that once left renters out is slowly being rebuilt. Young adults who can't afford a mortgage right now aren't necessarily falling behind. Many are finding a different way in.
Every on-time rent payment and utility bill adds up. Month after month of quiet financial reliability can help build a credit history over time.8
Building Toward Color
Maybe the dream hasn't disappeared. It's just being rebuilt differently.
For a lot of renters, turning rent and utility payments into reported credit history is a small but real step forward. It's a way of reclaiming some agency in a system that's felt stacked against first-time buyers for years.
I still think about that purple house sometimes. I haven't bought my own yet, but I'm still keeping the promise I made as a kid. Every rent payment I make, every bill I pay on time, is one more brushstroke toward it.
It might take longer to own outright. But there's a foundation being built in the meantime, payment by payment. If you're already paying rent and utilities on time every month, Ava's Rent & Utility Reporting can help put that history to work8, and pairing it with Ava's Save & Build Account can round out your credit profile further4 6. Ava can't promise a specific outcome, credit scores depend on your whole file, not one tool, but it can help make sure the bills you're already paying count for something.
Frequently Asked Questions
Does rent reporting help build credit history?
Rent reporting can help build credit history for renters who don't currently have a score or have a thin credit file. A randomized study from the Urban Institute, published in June 2025, found that positive-only rent reporting cut the share of participants without a credit score in half, from 16% to 8%. For people who are credit invisible, establishing a score at all is often the first step toward accessing other credit products.
How many people currently have their rent payments reported to the credit bureaus?
As of TransUnion's September 2025 analysis, 13% of consumers had their rent payments reported to the credit bureaus, up from 11% the year before. That share has been rising as more property managers and self-reporting tools become available.
Can rent payment history help you qualify for a mortgage?
It can, depending on your lender. In July 2025, the Federal Housing Finance Agency announced that lenders selling loans to Fannie Mae and Freddie Mac may now use VantageScore 4.0, which factors in rent payment history, when underwriting a mortgage. Lenders aren't required to use it, so it's worth asking your lender which credit score model they rely on if this matters to your application.
Does signing up for rent reporting hurt your credit history?
Ava's Rent & Utility Reporting is not a lending product and does not require a hard credit check to sign up, so enrolling on its own should not create a hard inquiry on your credit report. Your credit score may still increase or decrease over time based on your full credit file, and Ava cannot guarantee results.8
Is rent reporting the same as a credit builder loan?
No, they're different products. Rent reporting gives you credit history for bills you're already paying, with no new debt. A credit builder loan, like Ava's Save & Build Account, involves making scheduled loan payments toward a secured account, which is reported as an installment loan to the credit bureaus.4 6 Both can help build credit history; rent reporting simply doesn't require taking on a new loan.
Does Ava's Rent & Utility Reporting cost anything?
Yes. Ava charges a flat-rate membership fee for access to its credit and non-credit products, and membership fees apply.10 There's no separate charge for the rent and utility reporting feature itself beyond the membership.
Footnotes
4. Ava partners with a technology service provider of banking related services Priority Technology Holdings, Inc., to provide your Ava Secured Loan Account. Money transmission services relating to the Passport Program are provided by Priority, directly or through its subsidiary Finxera, Inc. (NMLS #1168701) or its authorized affiliates and contractors.
6. Ava is not a bank, Ava is a technology company that partners with technology service provider of banking related services Priority Technology Holdings, Inc., as well as Pier Lending LLC NMLS 2451164 in certain states to provide the Secured Loan Account. The Ava Credit Builder Mastercard® is issued by Patriot Bank, N.A., pursuant to a license from Mastercard® International Incorporated.
8. Ava reports your payment activity and tradelines ("Activity") to all 3 credit bureaus, with rent and utility reporting limited to TransUnion, but does not promise or guarantee specific results. Credit bureaus independently determine credit scores based on multiple factors which include non-Ava transactions. Ava has no influence over bureau processing times and cannot guarantee or predict how the bureaus will interpret or reflect your Activity. Activity may reflect differently across bureaus. Improvements to your credit score cannot be guaranteed. Your credit score may be impacted positively or negatively.
10. Ava charges a flat-rate membership fee to access all credit and non-credit products. Membership plans are monthly or annual.
Important Disclosures
Ava Finance is a financial technology company, not a bank. Certain loan and credit services are provided by Pier Lending LLC (NMLS #2451164) in select states. The Ava Credit Builder Mastercard® is issued by Patriot Bank, N.A., pursuant to a license from Mastercard International Incorporated.
Your approval for the Ava Credit Builder Card or Save & Build Account is not guaranteed. Successfully linking your bank account to Ava via Plaid is required for approval. Failure to maintain a Plaid connection may result in termination of your account.
Ava reports your payment activity and tradelines to all three credit bureaus. Rent and utility bureau reporting is limited to TransUnion. Credit bureau reporting is not guaranteed to improve your credit score. Credit bureaus determine scores independently based on multiple factors, including non-Ava transactions.
Ava charges a flat-rate membership fee for access to credit and non-credit products. Membership plans are monthly or annual.
Go to meetava.com for additional important disclosures regarding terms and conditions.
Sources
National Association of Realtors, 2025 Home Buyers and Sellers Generational Trends Report (published November 2025).
Consumer Financial Protection Bureau, Technical Correction and Update to the CFPB's Credit Invisibles Estimate (June 2025).
TransUnion, Rent Payment Reporting Analysis (September 2025).
Urban Institute, Evaluating Rent Reporting as a Pathway to Build Credit (June 2025).
Federal Housing Finance Agency, VantageScore 4.0 mortgage underwriting announcement (July 2025).